
Epizódjegyzetek
▶ Explore this week’s Tape — live, sortable, drill-down →
Wall Street Called PayPal Dead Money for Two Years. This Week, Private Capital Sent a Term Sheet.
Two markets looked at the same cash flows this week and reached opposite verdicts. The public market has spent two years pricing PayPal, Comcast, and half the telecom block as value traps — cheap for a reason, and the reason is they’re dying. Then Stripe and the private-equity firm Advent put fifty-three billion dollars on the table for PayPal at a twenty-eight percent premium, and PayPal’s own board came back and said the number was too low.¹² Only one of those two verdicts arrives with committed financing attached.
The tell isn’t the premium. It’s what the premium is buying.
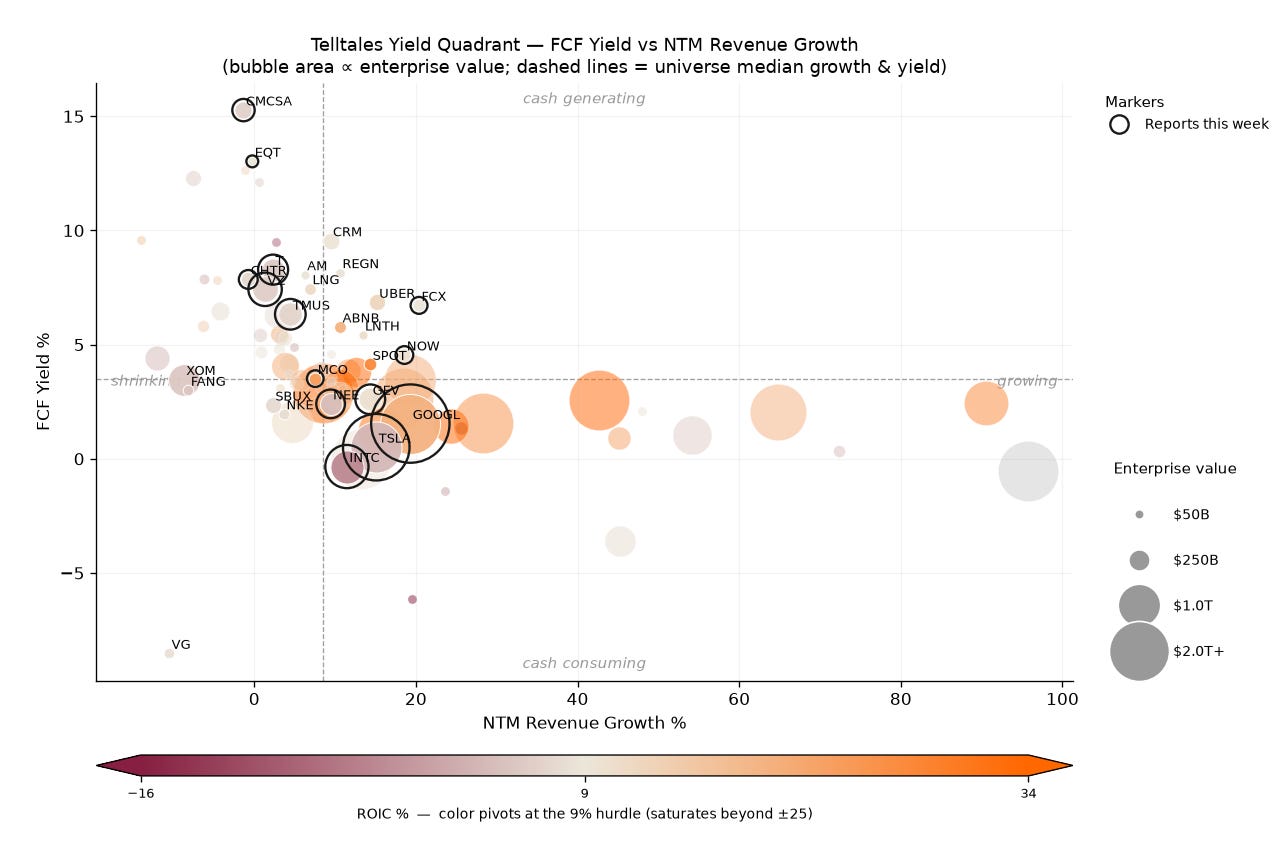
Start with the balance sheet, because that’s where the buyer started. PayPal carries almost no debt and throws off something close to a sixteen percent free cash flow yield.³ To a public shareholder, that yield is a warning — the market’s way of saying the branded-checkout business is in slow decline and the multiple should stay buried. To a private buyer, the exact same yield is fuel. A clean balance sheet generating that much cash finances its own buyout: you borrow against the cash flow, cover the interest several times over, and fix the growth story out of the public eye on a five-to-seven-year clock instead of a ninety-day one. The public market marks PayPal to next quarter’s narrative. Advent underwrites it to the end of the decade.
You could watch the plumbing for that trade get built in real time. Stripe and Advent lined up roughly fifty billion dollars in committed financing from JPMorgan and Morgan Stanley before the bid was even public, per Bloomberg.⁴ And in the same week, KKR started marketing bonds in Germany backed by PayPal’s buy-now-pay-later loans — the first securitization of its kind in Europe.⁵ That’s a second, entirely separate pool of lenders deciding PayPal’s receivables are money-good. When the assets underneath a company finance this easily, the buyout stops being speculative. The debt to do the deal is already there to be borrowed.
Here’s the part the show didn’t have room for: this is not really a PayPal story. It’s a repricing of the entire boring half of the Cash Flow Memo. The same math that turns PayPal into a buyout candidate is sitting on page six under the telecom block — Comcast at a fifteen percent yield, Verizon at seven, every one of them a low-growth cash machine the public market has left for dead.⁶⁷ This is the take-private-of-the-cash-cow playbook, the one that ran hot in 2006 and 2007 — except this cycle the fuel isn’t syndicated bank loans and high yield, it’s private credit: direct-lending funds and asset-backed securitizations that did not exist at anything like this scale a decade ago. A financing system that large doesn’t just make one deal possible. It makes the list of takeable public cash machines far longer than the public market has priced in.
The cashflow read is…
Weboldal: telltales.substack.com


