
Σημειώσεις επεισοδίου
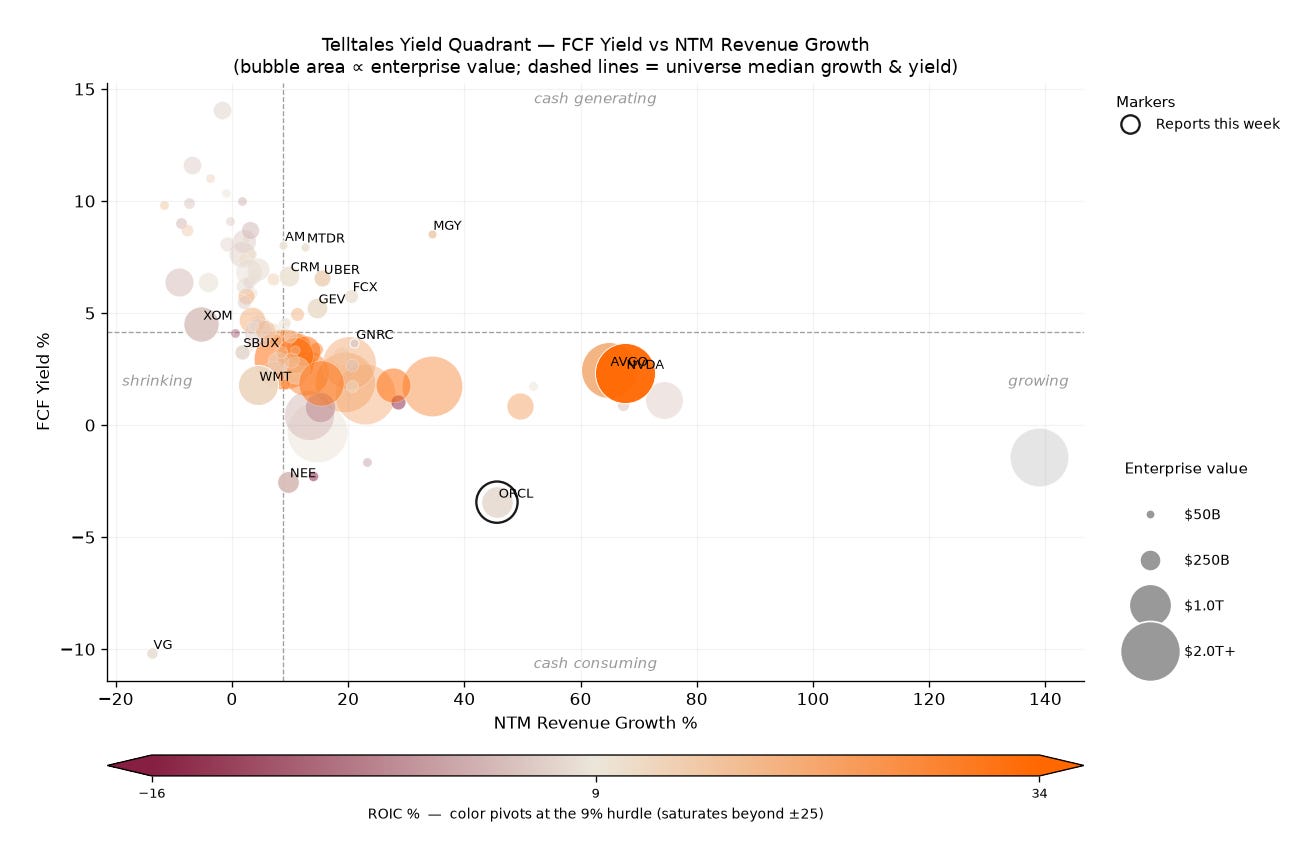
▶ Explore this week’s Tape — live, sortable, drill-down →
ONEOK Bought a Ratio
ONEOK announced a four-point-four-billion-dollar acquisition last weekend and raised nine billion dollars to pay for it. The gap between those two numbers is the story, and it is not what the headlines carried. Four-point-four billion buys Brazos Midstream’s Permian gathering and processing assets. Five billion retires debt¹. Page ten of the Cash Flow Memo carries ONEOK at about thirty-three billion dollars of net debt², so five billion is a real dent. The interesting part is which five billion, and what replaced it.
Start with what Apollo actually bought, because nine-billion-dollar minority equity investment conceals more than it reports. Apollo gets a Class B interest in a newly formed holding company, ONEOK Holdings, L.L.C. It is nonvoting. No board seat, no liquidation preference, structurally subordinate to every existing ONEOK bond. It is entitled to fifteen percent of the operating company’s quarterly cash flow, and its total return is capped at a seven percent internal rate of return for the first nine years. ONEOK can buy the whole thing back beginning on the eighth anniversary of closing, at that same capped return³. Apollo took a bond’s return while standing in an equity’s place in the stack.
Now what ONEOK bought. One sentence in the release explains the other twelve: the investment has been reviewed with ONEOK’s credit rating agencies, all of which consider the transaction as credit-enhancing, and ONEOK expects to receive full equity credit⁴. Every concession in the paragraph above is priced to earn that clause. This instrument was assembled by people who knew precisely which boxes a rating methodology checks. Pro forma 2027 leverage lands near three and a quarter times debt to EBITDA, and not one common share was issued⁵. Apollo, in the same release, called it flexible, high-grade capital solutions at scale, structured around ONEOK’s long-term strategic objectives. Translation: we found the boxes and built something that ticks all of them.
Then the tender offer, filed the same day and buried under the acquisition headline. ONEOK is offering to repurchase up to two billion dollars of its own notes across twenty series, and the acceptance priority order tells you what it wants back. Level one is the three-point-nine-five percent notes due 2050. Level two, four-point-two percent due 2047. The list runs long-dated and low-coupon at the top, and the company adds, in a parenthetical, that most of the targeted notes currently trade below par⁶ — below face value, because those coupons sit under what the market charges today. So ONEOK is retiring some of the lowest cash coupons on its balance sheet and funding the gap with money that costs seven percent. The cash cost of the capital went up. The ratio the agencies quote went down. Both by design.
None of that makes it a bad trade. Seven percent capped is genuinely cheaper than ONEOK’s cost of common equity…
Ιστότοπος: telltales.substack.com

